讲座题目 | Two-Sided Overconfidence in Corporate Credit: Financial Intermediation, Investment Efficiency, and Crisis Fragility | ||
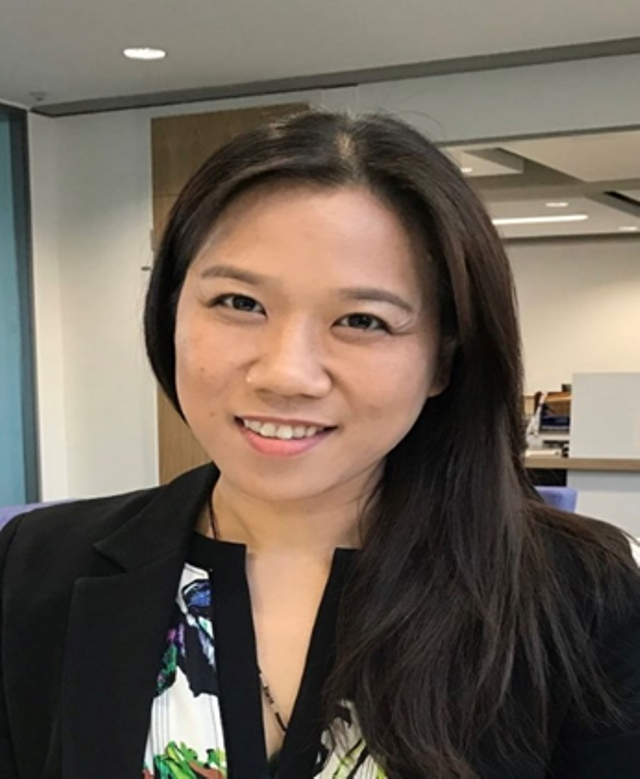
主讲人 (单位) | 赵天姝 (英国莱斯特大学) | 主持人 (单位) | 尹威 (电影天堂 ) |
讲座时间 | 2026年11月24日下午2点 | 讲座地点 | 教一103 |
主讲人简介 |
赵天姝博士现任University of Leicester 商学院金融学教授。她持有 Certified Public Accountant(CPA)资格,学术背景涵盖经济学、金融学和会计学。她的研究主要集中于金融中介、银行业微观经济学、公司金融以及 ESG 等领域,在《Journal of Banking and Finance》《Review of Economics and Statistics》《Regional Studies》《Journal of Economic Geography》《Journal of Financial Intermediation》《European Journal of Finance》等国际金融经济类顶尖期刊发表了多篇高影响力论文。 她曾主持或参与由DFID-ESRC 和 ESRC-NSFC 资助的重大科研项目,并与世界各地的中央银行、发展机构和高校开展合作。她长期与政策制定者保持密切合作,曾借调至 Welsh Government,参与中小企业融资和区域银行改革相关工作。此外,她还与 OECD、ECA 和 NIESR 等机构合作,开展可持续金融和信贷可得性等领域的研究。积极参与多个专业和学术组织的工作,现任 Money Macro and Finance Society 委员会委员以及 British Standards Institution(BSI)Sustainable Finance Committee 委员。她经常参加国际学术会议,并参与学术编辑及期刊相关工作。她曾担任 Central Bank of Uganda 和 University of Leuven 等机构的访问学者,并持续在学术界、政策部门和业界之间开展跨领域合作。 | ||
讲座内容摘要 | This paper examines how overconfidence on both sides of the corporate credit market affects credit allocation, loan contracting, and subsequent real outcomes. We develop a two-sided overconfidence framework in which overconfident firms have stronger latent demand for credit because they overestimate investment returns, while overconfident lenders underestimate the sensitivity of expected credit losses to additional lending. A realistic lender can therefore discipline an overconfident borrower's financing demand, whereas lender overconfidence weakens this external discipline. The central prediction is consequently an interaction effect: borrower overconfidence should translate more strongly into granted credit when the lender is also overconfident. Using syndicated loan data matched to borrower and lead-lender CEO characteristics, we find evidence consistent with this mechanism. The interaction between borrower and lender overconfidence is associated with larger granted loan quantities, whereas the corresponding one-sided effects are weaker and less stable. The additional credit accommodation is not matched by a commensurate adjustment in all-in spreads and is not broadly offset by systematically tighter non-price contractual terms, a pattern consistent with incomplete risk compensation in dual-overconfidence lending relationships. The interaction between borrower and lender overconfidence is also associated with subsequent real outcomes. Firms exposed to dual overconfidence exhibit higher investment and greater investment inefficiency, with the inefficiency concentrated on the overinvestment side. Moreover, firms with greater pre-crisis exposure to dual overconfidence experience weaker operating performance and lower abnormal stock returns during the financial crisis. Overall, the evidence suggests that the consequences of managerial overconfidence depend importantly on financial intermediation: lender beliefs can either discipline distorted financing demand or amplify its transmission into credit expansion, inefficient investment, and downside fragility. | ||